

Short Sale — Live Market Pulse & Sold Scorecard
Anchored on Highlands Ranch ZIP codes 80126, 80129 & 80130 to automatically capture all listings entered under both "Highlands Ranch" and "Littleton" postal cities.
• Single-Family Detached: 78 Active · 86 Sold · Median Sold: $700,000 (Avg: $795,187 · $293/SqFt)
• Condos & Townhomes: 19 Active · 14 Sold · Median Sold: $521,867 (Avg: $526,830 · $323/SqFt)
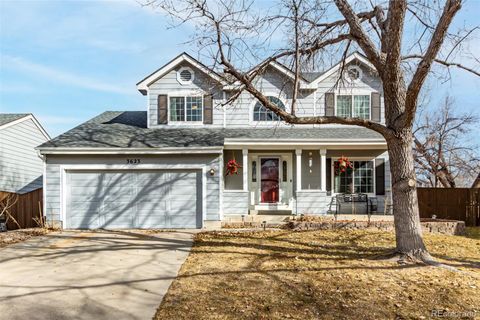
- 864 English Sparrow Trail — $625,000 · 3 Bed · 4 Bath · 2,500 SqFt · Highlands Ranch (Listing courtesy of Serhant Colorado LLC via REcolorado)
- 10636 Wildhurst Circle — $699,000 · 0 Bed · 0 Bath · 2,647 SqFt · Highlands Ranch Firelight (Listing courtesy of Mainstay Brokerage LLC via REcolorado)
- 1384 Shadow Mountain Drive — $950,000 · 6 Bed · 4 Bath · 3,641 SqFt · Highlands Ranch (Listing courtesy of KOIS REAL ESTATE via REcolorado)
- 10828 Cedar Brook Street — $745,000 · 3 Bed · 3 Bath · 2,562 SqFt · Highlands Ranch (Listing courtesy of Redfin Corporation via REcolorado)
- 9647 Cove Creek Drive — $619,000 · 3 Bed · 3 Bath · 1,817 SqFt · Westridge (Listing courtesy of Steven E Crozier, Independent Broker via REcolorado)
- 4244 Lark Sparrow Street — $630,000 · 3 Bed · 4 Bath · 2,438 SqFt · Highlands Ranch (Listing courtesy of One Stop Realty, LLC via REcolorado)
Market statistics calculated from live REcolorado IDX feed (excluding rentals and non-arm's-length entries). Have questions about a specific street, lot orientation, or remodeling layout (basements, decks, landscaping, kitchens)? Call/text Saber Amine (Owner & Designated Broker, Homes and People, Colorado Real Estate License #ER40029599) at 720-842-1600 or Contact Saber.


Skip the endless search filters. Tap the microphone icon inside our AI Concierge—or type your command—to find Highlands Ranch short sales, price reductions, fixer-uppers, or homes by price and neighborhood, plus get instant builder and closing answers.
Why Short Sales Happen in Highlands Ranch & How Banks Price Them
Because Highlands Ranch is one of the highest-equity master-planned communities along the Denver South Metro corridor, true short sales are rare—and when they surface inside our Hot Properties feed, they attract immediate attention from both value-conscious homebuyers and seasoned investors. A short sale occurs when a homeowner experiences a verified financial hardship and owes more on their combined mortgage and home-equity loans (plus closing costs) than the property can command in its current physical condition.
Unlike a traditional resale where the homeowner alone decides whether to accept your offer, a short sale is governed by the mortgage servicer's loss-mitigation department. Once the seller signs your contract, the lender orders an independent Broker Price Opinion (`BPO`) or full interior appraisal to establish "As-Is" fair market value. If your offer aligns with the bank's net recovery threshold—typically factoring in the condition discounts that retail buyers demand—the lender issues a formal written approval releasing the mortgage lien so you can acquire the property prior to a public auction.
How Short Sale Profiles Differ Across Highlands Ranch Build Eras
Not every short sale is a dilapidated fixer-upper. Depending on which Highlands Ranch village and construction era a property belongs to, the underlying cause of the short payoff—and the physical inspection risk you assume as the buyer—varies dramatically:
| Highlands Ranch Build Era | Typical Short Sale Trigger & Lien Profile | Builder & Engineer Due-Diligence Focus |
|---|---|---|
| Newer Construction & Recent Custom Resale (2015–Present) | Usually driven by sudden executive relocation, divorce, or a high-loan-to-value purchase within the past 12 to 36 months where transaction costs push the payoff above current resale value. | Core structural, 200-amp electrical, and PEX plumbing systems are modern; verify builder structural warranty transferability, check for unfinished walkout basements or unfinished backyard grading, and confirm mechanic's lien releases from recent contractors. |
| 2000s & 2010s Luxury & Move-Up Villages (Backcountry, Tresana, Firelight, Golf Club) | Often involves a primary jumbo mortgage paired with a secondary Home Equity Line of Credit (HELOC) or business collateral lien, combined with dated 2000s interior finishes that reduce retail buyer offers. | Audit multi-zone HVAC condensers, custom roof tile or heavy architectural shingles, expansive composite or cedar deck substructures, and calculate the cost of modernizing kitchens and primary baths to unlock full neighborhood ARV. |
| Established 1980s & 1990s Villages (Northridge, Eastridge, Westridge, Southridge) | Frequently caused by cash-out refinancing layered onto heavy deferred capital maintenance, where roof wear, original windows, or mechanical failures cause retail buyers to sharply discount the property. | Inspect for grey polybutylene supply piping (1978–1995), undersized or recalled 100-amp to 125-amp electrical panels, freeze-cracked copper or PEX lines if vacant over winter, and foundation slab heaving from unmaintained gutters over expansive clay soils. |
When a short sale surfaces in a premier luxury village like Backcountry, Firelight, or The Hearth, the physical house is often structurally sound, featuring modern 200-amp electrical service, tall ceilings, and engineered foundations. In those cases, the complexity lies in negotiating with both the primary mortgage servicer and a secondary HELOC lender while pricing in cosmetic updates to the kitchen, basement, or outdoor deck. Conversely, in older 1980s and 1990s subdivisions, financial distress almost always correlates with years of deferred exterior and mechanical upkeep.
A Builder & Engineer's "As-Is" Physical Inspection Protocol
Every short sale addendum in Colorado stipulates that the property is sold strictly **"As-Is."** Because the lender is already taking a loss on the loan payoff and the distressed homeowner has no cash reserves, you will not receive inspection repair credits or seller-paid roof replacements at closing. However, "As-Is" never means waiving your right to inspect.
As a residential builder, home rehab expert, and engineer, I evaluate every short sale alongside my buyers to quantify both hidden physical liabilities and post-closing remodel potential:
- Winterization, Plumbing & Freeze-Damage Audits: If a distressed property sits vacant during a Front Range freeze cycle with utilities shut off, water trapped inside baseboard loops, hose bibs, main-level kitchen islands, or basement manifolds can split pipes behind the drywall. We verify pressure integrity and check 1980s–1990s homes for brittle polybutylene piping before your inspection objection deadline expires.
- Electrical Service Panels & Unpermitted Wiring: Homeowners facing financial stress frequently attempt DIY basement finishes or kitchen updates without pulling Douglas County permits. I help you know what to ask your licensed inspector regarding the main load center for improper double-tapped breakers, missing arc-fault (`AFCI`) or ground-fault (`GFCI`) protection, overloaded subpanels, and outdated 100-amp service capacities.
- Foundation Grading, Roof Envelopes & Deck Ledgers: Clogged gutters and disconnected downspouts dump thousands of gallons of snowmelt directly against the foundation wall, activating Douglas County's expansive bentonite clay soils. We check basement structural walls, floating partition tolerances, hail-bruised roofing shingles, and exterior deck ledger-board flashing so every capital expense is baked into your offer price.
- Post-Closing Kitchen, Basement, Deck & Landscaping Value-Add: Once we verify the structural and mechanical baseline, we map out high-ROI architectural improvements—such as removing a load-bearing wall to open up a cramped kitchen layout, finishing a walkout basement, rebuilding an elevated composite deck, or regrading the backyard landscaping—to maximize your instant equity after closing.
Navigating Bank Approvals, Public Trustee Deadlines & HOA Clearances
Successfully closing a short sale in Highlands Ranch requires disciplined contract structuring and active tracking of statutory foreclosure deadlines. If a Notice of Election and Demand (`NED`) has already been recorded with the Douglas County Public Trustee, the transaction is racing against a fixed statutory auction clock—a process we break down step by step in our Colorado Foreclosure Timeline Explained Guide. If the lender fails to postpone the sale date or if the seller's debt exceeds what junior lienholders will release, the property may proceed to the courthouse steps and transition onto our Bank-Owned & Auction Homes page.
To protect your earnest money and timeline during the 60-to-180-day bank review period, we structure our short sale addendums so that your formal inspection and appraisal deadlines do not start ticking until **after** the lender delivers written short sale approval. Simultaneously, buyers and their licensed inspectors should review the preliminary title commitment for delinquent property taxes, municipal water liens, and any open Highlands Ranch Community Association (`HRCA`) architectural violations or past-due assessments so that you receive clean, insurable title at the closing table.
Frequently Asked Questions
What is a short sale in Highlands Ranch real estate?+
How long does it take to close on a short sale in Douglas County?+
Are short sale homes in Highlands Ranch sold strictly As-Is?+
How do short sale properties differ across Highlands Ranch build eras?+
Can I finance a Highlands Ranch short sale with a conventional or FHA mortgage?+
What happens to unpaid HOA assessments or municipal liens during a Highlands Ranch short sale?+
Highlands Ranch Realtor, residential builder, home rehab expert, and engineer sharing general construction knowledge, layout and remodeling ideas for basements, decks, landscaping, and kitchens, and helping clients know what questions to ask independent licensed inspectors across Douglas County.
Evaluating a Highlands Ranch short sale or exploring options to avoid foreclosure?
Read Saber's Builder & Engineer Bio or reach out directly for a confidential consultation.